Will or Gift Deed in India 2026? Costs, Control, Tax and What Can Be Undone
This guide explains the legal meaning, process, and practical decision framework for choosing between a Will vs Gift Deed in 2026, as applicable in India.
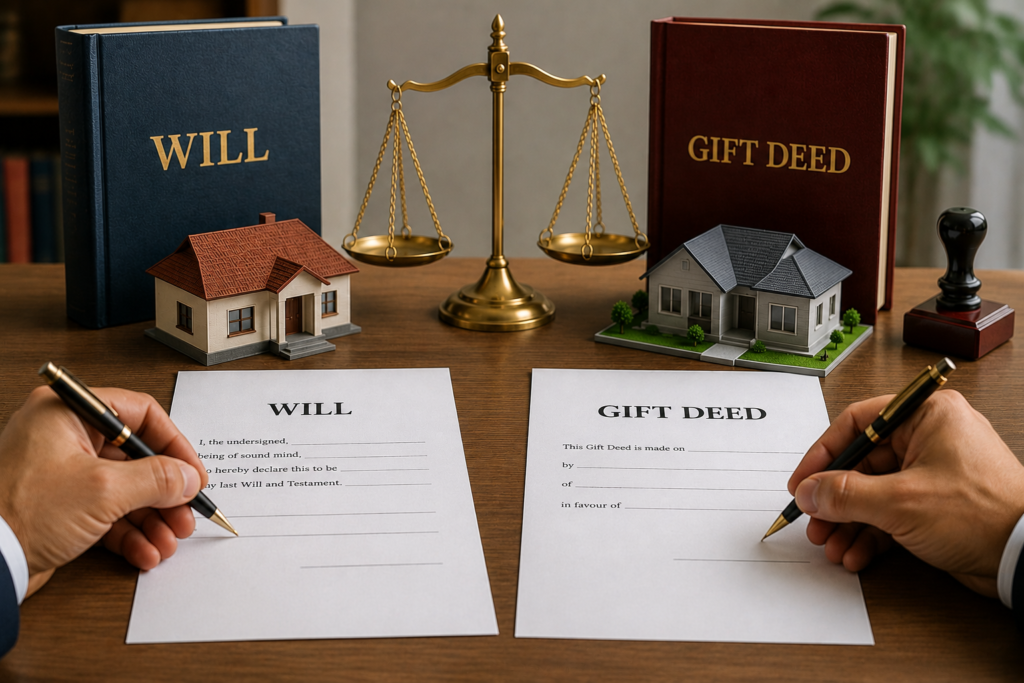
Will or Gift Deed in India 2026? Costs, Control, Tax and What Can Be Undone
If you are deciding whether to hand the flat to your son now by gift deed or leave it to him in your will, the two routes differ on the day they take effect and on what they cost. A gift deed moves the property while you are alive, has to be registered at the Sub-Registrar's office under section 17(1)(a) of the Registration Act, 1908, and carries stamp duty at the state's rate, which in Delhi is 4 per cent where the receiver is a woman and 6 per cent where the receiver is a man. A will moves nothing until you die, carries no stamp duty at all, and you can change it as often as you like.
A registered gift deed cannot be cancelled just because you change your mind, and the income tax exemption applies only to a closed statutory list of relatives. Where the donor is a senior citizen who gave the property on the condition of being looked after, a separate statute decides whether it can come back.
Where this page sits
What the decision turns on: when each route takes effect, what each costs at the Sub-Registrar in Maharashtra, Delhi and Karnataka, who pays income tax on what is received, and what can be undone after it is signed.
If you have already settled on a gift deed and only need the duty worked out for your state, or you signed one and now want it cancelled, the two guides below go further than this page does.
Related guides:
- Stamp duty on a gift deed in Maharashtra
- Can a gift deed be revoked after registration
- What registering a will actually buys
- A will drafted around your family
Which is Better, a Will or a Gift Deed?
A gift deed is better where the decision is already settled and you want it done in your lifetime. The flat moves to your son on the day the deed is registered and he accepts it. A will is better in every other situation, because you keep the property, you keep the right to sell it or mortgage it, and you can rewrite the will as often as your circumstances change.
Whether a gift deed or a will is better for your family turns on what it costs on the day, on how much control you keep, and on who is receiving the property. A gift deed carries stamp duty at your state's rate and a will carries none. A registered gift cannot be taken back on a change of mind, while a will can be replaced at any time. Income tax does not apply to a gift to a close relative, and it does tax a gift to a nephew or a cousin. Anything received under a will is not taxed, whoever receives it.
If you are a senior citizen handing property to a child who is meant to look after you, the maintenance condition has to be written into the deed itself for the law to help you afterwards.
What is the Legal Difference Between a Will and a Gift Deed?
The legal difference between a will and a gift deed is when ownership moves. A gift deed moves it on the day the gift is accepted and the deed is registered, and a will moves nothing until the testator has died.
Section 122 of the Transfer of Property Act, 1882 defines a gift as the transfer of certain existing movable or immovable property made voluntarily and without consideration, by one person called the donor to another called the donee, and it requires the donee to accept it. That acceptance has to be made during the donor's lifetime and while the donor is still capable of giving. If the donee dies before accepting, the gift is void. Once the gift is accepted and the instrument is registered, the donor has given the property away on that day and keeps no ownership in it.
A will is a different kind of document and is governed by the Indian Succession Act, 1925. It carries your directions for distributing your property after your death, and it creates no rights in that property for anyone while you are alive. You stay the owner, and you can sell the flat or mortgage it exactly as you could before you wrote the document. The people named in the will receive nothing until the testator dies.
Both documents are signed in front of two witnesses, and each statute adds its own requirements. Section 123 of the Transfer of Property Act, 1882 requires a gift of immovable property to be effected by a registered instrument, signed by or on behalf of the donor and attested by at least two witnesses, while a gift of movable property may be effected either by such a registered instrument or by delivery.
For a will, section 63 of the Indian Succession Act, 1925 sets the execution rules. The testator signs the will or affixes a mark to it, and two or more witnesses attest it, each of whom has either seen the testator sign or received a personal acknowledgement of the signature from the testator. Each witness signs in the presence of the testator.
Tell us who you want to provide for and what you own, and a WillJini lawyer will tell you whether a will covers it.
How Does the Registration Process Differ for Both?
Registration is compulsory for a gift deed and optional for a will, and the two documents go into different registers at the Sub-Registrar's office.
Section 17(1)(a) of the Registration Act, 1908 makes registering an instrument of gift of immovable property compulsory. Until that registration happens, the property has not legally transferred to the donee. Section 18(e) of the same Act puts a will on the optional list, so a validly executed unregistered will carries the same legal weight as a registered one, and clause (a) carves gifts and wills out of the rest of that optional list.
A registered gift deed goes into Book 1, the public register of non-testamentary documents relating to immovable property, and anyone may inspect Book 1 and apply for a certified copy of a registered gift deed. A will that you choose to register goes into Book 3 instead, under section 51(1), and Book 3 is the register of wills and authorities to adopt rather than a property register.
Section 57(2) decides who may have a copy of that Book 3 entry: the testator or the testator's agent during the testator's life, and after the death, any person who applies. Section 57(5) then sets out what that copy is worth: every copy given under the section is signed and sealed by the registering officer and is admissible for the purpose of proving the contents of the original document.
Can You Revoke a Gift Deed or a Will After Execution?
A will can be revoked at any time before the testator dies, and a registered gift deed cannot be revoked simply because the donor has changed his mind.
Section 70 of the Indian Succession Act, 1925 sets out how an unprivileged will is revoked: by the execution of another will or codicil, by a signed and witnessed writing declaring the intention to revoke, or by the testator destroying the document with the intention of revoking it. Section 70 also lists marriage, but Schedule III of the Act removes those words for the will of a Hindu, Buddhist, Sikh or Jain, and the proviso to section 57 says marriage shall not revoke any such will. For most Indian testators, therefore, marrying does not cancel the will they already made. You can write and revoke as many wills as you choose during your lifetime, and the last valid one stands.
Section 126 of the Transfer of Property Act, 1882 allows a gift to be revoked in two situations. The donor and the donee may agree that the gift is suspended or revoked on the happening of a specified event which does not depend on the will of the donor, and a gift the parties agree is revocable wholly or in part at the mere will of the donor is void wholly or in part, as the case may be. A gift may also be revoked in any of the cases in which it might be rescinded if it were a contract, save for want or failure of consideration. Neither ground is open to a donor who has merely changed his mind about the gift.
How Does the Senior Citizens Act Protect Elderly Donors?
An elderly donor who gifted property on the condition of being looked after, and is then not looked after, can cancel the transfer without having to prove fraud. That right comes from section 23(1) of the Maintenance and Welfare of Parents and Senior Citizens Act, 2007.
The section provides that where a senior citizen has transferred property by way of gift or otherwise, subject to the condition that the transferee shall provide the basic amenities and basic physical needs to the transferor, and the transferee refuses or fails to provide those amenities and physical needs, the transfer shall be deemed to have been made by fraud or coercion.
The application goes to the Maintenance Tribunal, which is the forum section 23(1) names, and the transfer is declared void at the option of the transferor. Section 23(1) only reaches a transfer that was made subject to that condition, so the condition has to be written into the gift deed when the deed is drawn up. A bare gift deed that says nothing about maintenance does not engage the section, and an elderly parent who has signed one is left with section 126 and the ordinary burden of proving fraud or coercion. Where the condition is in the deed, the parent does not have to prove that the child acted fraudulently on the day of signing, because the statute deems the transfer to have been made by fraud or coercion once the maintenance stops.
A parent who leaves the flat by will never faces the question at all, because the property stays in his own name for life and the will can be rewritten at any time.
How is Income Tax Calculated on a Gift or a Will?
Nothing received under a will is charged to income tax, and a gift is charged on the person receiving it unless the donor is a relative on a closed statutory list. Both rules sit in the Income-tax Act, 2025, which has governed these receipts since 1 April 2026.
Section 92(2)(m) charges the receiver of money or property given without consideration. If you receive a sum of money without consideration and the total exceeds Rs 50000 in a tax year, the whole sum is your income for that year. If you receive immovable property without consideration and its stamp duty value exceeds Rs 50000, you are charged on that stamp duty value.
Section 92(3) then takes four receipts out of the charge: anything received from a relative, anything received on the occasion of the marriage of the individual, anything received under a will or by way of inheritance, and anything received in contemplation of the death of the payer or donor.
For a son, a daughter, a brother or a sister, neither route attracts income tax. A gift from a relative is outside the charge under section 92(3)(a), and everything received under a will is outside it under section 92(3)(c). For a close family member the choice is therefore made on the stamp duty and on whether you want to keep control of the property while you are alive.
Section 92(5)(g) sets out a closed list of relatives, and it is narrower than the word family. Section 92(5)(g) covers, for an individual, the spouse, a brother or sister, a brother or sister of the spouse, a brother or sister of either of the parents, any lineal ascendant or descendant, any lineal ascendant or descendant of the spouse, and the spouse of any of those persons. For a Hindu undivided family it means any member of it. The list includes your wife's brother and does not include your own nephew.
If the flat you want your brother's son to have is worth Rs 60 lakh, gifting it to him now means he is charged income tax on its stamp duty value, because a nephew is not on the section 92(5)(g) list and section 92(2)(m) charges the person receiving the property. Leave him the flat in your will instead and no income tax arises on what he receives, because section 92(3)(c) takes receipts under a will out of the charge whatever the relationship. A niece and a cousin stand exactly where the nephew stands, and for all three, a gift is taxed and a will is not.
Capital gains do not arise on either route at the moment of transfer. Section 70(1)(b) of the Income-tax Act, 2025 keeps the capital gains provisions from applying to the transfer of a capital asset by an individual or a Hindu undivided family under a will or a gift or an irrevocable trust. When the person who received the property sells it later, section 73(1) gives them the previous owner's cost of acquisition, increased by the cost of any improvement the previous owner paid for. That rule is the same whether the property came by gift or by will.
Why Does a Gift Deed Attract Stamp Duty and a Will Does Not?
A gift deed is one of the instruments the Indian Stamp Act, 1899 charges with duty, and a will is not one of them. Section 3 of that Act makes only the instruments mentioned in Schedule I chargeable, and Article 33 of that Schedule, which charges an instrument of gift, excludes a will from the gift charge by name. Schedule I carries no article for a will anywhere else either.
Maharashtra, Delhi and Karnataka charge different rates on a gift deed.
A WillJini lawyer drafts the will around your property and your family, and can register it for you afterwards.
What is the Cost Difference in Maharashtra?
In Maharashtra a will costs Rs 100 to register and carries no stamp duty, while the stamp duty on a gift deed runs from Rs 200 up to the conveyance rate depending on who receives the property and what kind of property it is.
Under Article 34 of the Maharashtra Stamp Act, a gift is charged at the conveyance rate on the market value by default, and two provisos bring that down. Where the donee is the husband, wife, brother, sister or any lineal ascendant or descendant of the donor, the duty is 3 per cent of the market value. Under the second proviso to Article 34, where residential or agricultural property is gifted to a husband, wife, son, daughter, grandson, grand-daughter or the wife of a deceased son, the duty is Rs 200.
That Rs 200 is a stamp duty figure, and the registration fee is charged separately on top of it. For the same family list, Note 59 to the Table of Fees has fixed that fee at Rs 200 since 1 April 2016. Outside that list the fee is charged on the value of the property and is capped at Rs 30,000, and the Maharashtra gift deed rates page works both charges out in full.
What is the Cost Difference in Delhi?
Delhi charges stamp duty and transfer duty on a gift deed at 4 per cent where the donee is a woman and 6 per cent where the donee is a man, with a registration fee of 1 per cent of the total value plus Rs 100 in pasting charges. A will costs Rs 600 to register and attracts no stamp duty at all.
The Revenue Department publishes those same two rates for a sale deed on the same property registration page. No family concession on a gift deed appears anywhere on it, so a father transferring a flat to his daughter pays the same 4 per cent that a woman buying the flat in an ordinary sale would pay.
No third rate is published for a joint donee, a man and a woman receiving the property together. The property being gifted has to be valued by an approved valuer before the deed is presented.
For a will, the testator and two witnesses have to be present at the Sub-Registrar's office when the document is presented for registration.
What is the Cost Difference in Karnataka?
Karnataka charges a fixed amount of stamp duty on a gift within the family and a share of the property's value on a gift outside it. A will attracts nil stamp duty and a registration fee of Rs 200.
In the Karnataka stamp duty and registration fee table, where the donee is a specified family member of the donor, the duty is Rs 5000 for property in BMRDA, BBMP or a City Corporation, Rs 3000 in a City or Municipal Council or Town Panchayath, and Rs 1000 for other areas. The registration fee on that deed is a flat Rs 1000, whatever the property is worth.
Where the donee is not a specified family member, the stamp duty is 5 per cent on the market value, plus a surcharge and an additional duty, and the registration fee is 2 per cent. Karnataka raised that registration fee from 1 per cent to 2 per cent with effect from 31 August 2025.
How Does WillJini Assist With Estate Planning?
WillJini drafts wills and sets up family trusts for families across India.
WillJini reviews your ownership documents and your family position, drafts the will, and has it executed the way section 63 of the Indian Succession Act, 1925 requires, with the testator's signature and two attesting witnesses.
The will names your executors and sets out how your property is distributed. Registration is optional, and where you want the will entered in Book 3 under the Registration Act, 1908, WillJini takes you through registering the will at the Sub-Registrar's office.
Send us your family details and what you own. Your lawyer takes it from there and nothing is final until you approve it.
FAQs
Which is better, a will or a gift deed?
A gift deed is better where you are certain and want the transfer completed in your lifetime, and a will is better where you want to keep the property and the freedom to change your mind. A gift deed carries stamp duty at your state's rate on the day it is registered, and a will carries none. Where the person receiving the property is not on the list of relatives at section 92(5)(g) of the Income-tax Act, 2025, a gift is taxed in their hands and a bequest under a will is not.
What is the legal difference between a will and a gift deed?
Under section 122 of the Transfer of Property Act, 1882, a gift deed transfers existing property immediately during your lifetime, and you lose all ownership rights once the registered gift is accepted. Under the Indian Succession Act, 1925, a will only takes effect after your death, leaving you with absolute control and full ownership of your property while you are alive.
Do you have to register a will in India?
No. Section 18(e) of the Registration Act, 1908 makes the registration of a will optional. An unregistered will that is validly executed under section 63 of the Indian Succession Act, 1925 carries full legal weight. A gift of immovable property requires compulsory registration under section 17(1)(a) of the Registration Act, 1908.
Can a registered gift deed be cancelled?
Generally no, but section 126 of the Transfer of Property Act, 1882 allows revocation if the donor and donee agreed that the gift would be suspended or revoked on a specified event not dependent on the donor's will. A gift agreed to be revocable at the mere will of the donor is void. Where the donor is a senior citizen and the deed carried a maintenance condition, section 23(1) of the Maintenance and Welfare of Parents and Senior Citizens Act, 2007 is a separate route. A will can be revoked at any time before death under section 70 of the Indian Succession Act, 1925.
What happens if a senior citizen is not maintained after gifting property?
Section 23(1) of the Maintenance and Welfare of Parents and Senior Citizens Act, 2007 provides a statutory remedy. If an elderly parent transfers property subject to a condition that the transferee provides basic amenities and basic physical needs, and the transferee fails to do so, the Maintenance Tribunal may declare the transfer void at the option of the parent. The transfer is deemed to have been made by fraud or coercion. The parent does not have to prove actual fraud in court, provided the condition is written in the deed.
Are gifts to nephews and nieces taxed in India?
Yes. Under section 92(2)(m) of the Income-tax Act, 2025, a person receiving property without consideration whose stamp duty value exceeds Rs 50000 is charged on that stamp duty value. Section 92(3)(a) exempts a gift from a relative, and section 92(5)(g) defines relative as a closed list. A nephew, a niece and a cousin are not on that list, so the gift is taxed in their hands. Anything received under a will is exempt regardless of the relationship under section 92(3)(c).
What is the stamp duty on a gift deed in Maharashtra?
Under the Maharashtra Stamp Act, the default rate is the conveyance rate. For a husband, wife, brother, sister or lineal ascendant or descendant, the duty is 3 per cent. Under the second proviso to Article 34, the stamp duty is Rs 200 for residential or agricultural property gifted to a husband, wife, son, daughter, grandson, grand-daughter or the wife of a deceased son. The registration fee is charged separately and is capped at Rs 30,000.
Does Delhi offer a stamp duty concession for gifting property to a child?
No. The Revenue Department of Delhi publishes no family concession on a gift deed. The property must be valued by an approved valuer, and the rates are the same as sale deed rates. The stamp duty and transfer duty is 4 per cent if the donee is a woman, and 6 per cent if the donee is a man. The registration fee is 1 per cent of the total value plus Rs 100 pasting charges.
What is the registration fee for a gift deed in Karnataka?
For a donee who is not a specified family member, Karnataka charges 5 per cent stamp duty and a registration fee of 2 per cent, raised from 1 per cent with effect from 31 August 2025. For a specified family member, the stamp duty is a flat figure by location, reaching Rs 5000 in BMRDA, BBMP and City Corporation areas, and the registration fee is Rs 1000. A will in Karnataka carries nil stamp duty and a registration fee of Rs 200.
Every figure, office and timeline on this page traces to a government publication. Where the state publishes nothing, this page says so.
- Transfer of Property Act, 1882, section 122 gov.inWhat a gift is, and that acceptance must happen in the donor’s lifetime
- Transfer of Property Act, 1882, section 123 gov.inA gift of immovable property needs a registered instrument and two attesting witnesses
- Transfer of Property Act, 1882, section 126 gov.inWhen a gift may be suspended or revoked
- Registration Act, 1908, section 17 gov.inRegistering a gift of immovable property is compulsory
- Registration Act, 1908, section 18 gov.inA will may be registered, which makes it optional
- Registration Act, 1908, section 51 gov.inBook 3, the register of wills
- Registration Act, 1908, section 57 gov.inWho may have a copy of a registered will, and that the copy proves the contents
- Indian Succession Act, 1925, section 63 gov.inHow a will is executed
- Indian Succession Act, 1925, section 70 gov.inHow a will is revoked
- Maintenance and Welfare of Parents and Senior Citizens Act, 2007, section 23 gov.inThe senior citizen’s route to have a conditional transfer declared void
- Income-tax Act, 2025, Gazette CG-DL-E-22082025-265620 gov.inSections 70(1)(b), 73(1), 92(2)(m), 92(3), 92(5)(g) and 536(1)
- Maharashtra Stamp Act, Schedule I, Article 34 gov.inThe 3 per cent family rate and the Rs 200 proviso
- Department of Revenue, Government of NCT of Delhi gov.inGift deed and will charges in Delhi
- Department of Stamps and Registration, Karnataka gov.inGift deed and will deed charges in Karnataka
- Maharashtra Revenue and Forest Department notification, 31 March 2016 gov.inNote 59 to the Table of Fees, the Rs 200 registration fee on a family gift of residential and agricultural property

Jatin founded WillJini to make succession paperwork survivable for ordinary families, in a country where the office that issues a document, the fee it carries and the time it takes all change at the state line. He has been a member of the Institute of Company Secretaries of India since January 1995.
- B.G.L., University of Mumbai
- Company Secretary
- ICSI member since 1995
Every page in this guide series is reviewed against the issuing department’s own published material before it goes up. Where a state publishes nothing, the page says so.
Other articles for you